
In this analysis
01 · The Right International Gold Structure02 · The Quality Difference: Specifically Allocated Bars03 · Switzerland: Our Core European Solution04 · Dubai and Turkey: Our GCC Solution from EUR 100,00005 · Singapore and Hong Kong: Asian Options on Request06 · Four Locations—Four Strategic Opportunities07 · Multiple Locations Create International Optionality08 · What Professional Custody Looks Like09 · Our Quality Review Before ImplementationThe Right International Gold Structure
A professional gold solution connects four elements: acquisition, legal ownership, international custody, and a clear path to sale. The better these functions work together, the stronger gold becomes as a long-term wealth asset.
Four layers must be assessed separately:
- Acquisition and settlement: Who sells the gold? Which entity issues the invoice? When does legal title transfer?
- Legal ownership: Do you own identifiable bars, or merely a claim against a provider?
- Physical custody: Where is the metal actually stored? Who is the vault operator? Are sub-custodians involved?
- Access and exit: How do physical delivery, transfer, resale, and settlement work—including after a change of residence, incapacity, or death?
These layers may sit in one jurisdiction, but they do not have to. A European solution, for example, may use an investment or settlement route in Liechtenstein while storing the physical metal in Switzerland. A GCC-focused structure may organize market access through Dubai while intentionally separating long-term custody. For an internationally positioned family, Singapore may provide an independent Asian axis.
This is not needless complexity. It is the deliberate separation of functions. A gold structure usually becomes complex not because several locations are involved, but because the contracts among several parties are unclear.
A durable gold structure separates acquisition, ownership, custody, and exit—and reconnects them only after verification.
The Quality Difference: Specifically Allocated Bars
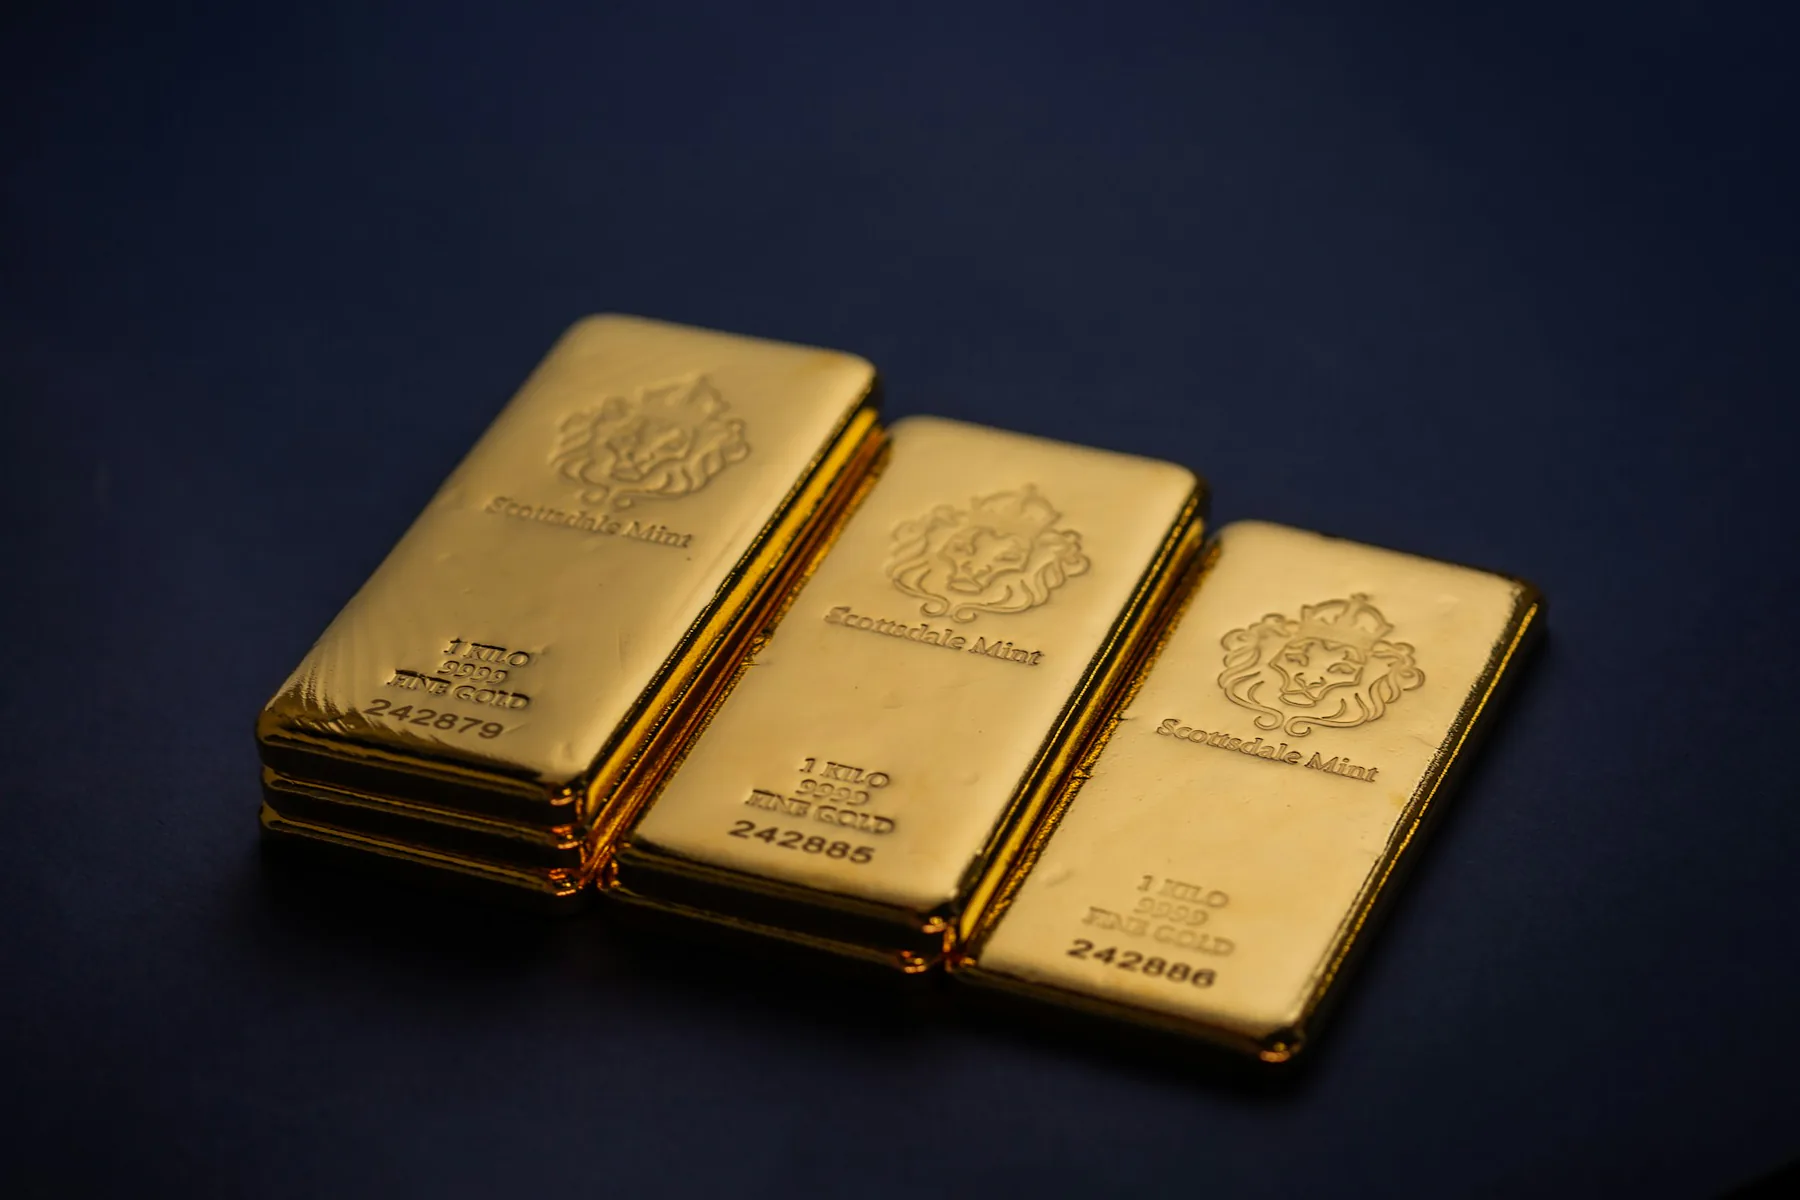
With allocated custody, identifiable bars are assigned to the owner by refiner, serial number, weight, and fineness. Segregated custody can add physical separation, creating transparency and traceability.
The London Bullion Market Association distinguishes between allocated and unallocated accounts in the professional precious-metals market. An unallocated account generally gives the account holder a claim against the provider for a specified quantity of metal. Specific bars, however, are not individually assigned to the client, leaving credit and counterparty exposure to the provider.
With allocated custody, specific bars are assigned. A credible bar list will typically identify the refiner or manufacturer, serial number, weight, and fineness. Yet even the word “allocated” should not end the inquiry.
You still need to establish:
- Is the client the legal owner, or only the beneficial owner?
- Does the physical custodian recognize the client directly—or only a dealer, platform, or nominee?
- May the metal be lent, pledged, substituted, or otherwise used?
- Do liens, rights of retention, or setoff rights exist?
- Is the metal physically segregated, or merely accounted for separately?
- What happens if the dealer, platform, custodian, or sub-custodian becomes insolvent?
Allocated and segregated are not the same. An allocated bar can be assigned unequivocally to one client while remaining on a pallet with other clients' holdings. Segregation describes a greater degree of physical separation—for example, a client-specific compartment, container, or sealed holding. Because the term is not used consistently worldwide, the agreement must define exactly what is being separated.
A serial number is therefore strong evidence, but it is not a universal insolvency guarantee. What matters is the complete documentary chain: purchase agreement, transfer of title, bar list, custody agreement, acknowledgment by the vault operator, exclusion of conflicting rights, audit evidence, and the treatment of the asset under the applicable insolvency law. This article therefore does not assert that client metal in any particular jurisdiction will always remain outside an insolvency estate. Before making a significant allocation, a written review under the law governing the actual contract and storage location should establish what delivery, separation, proprietary, or other rights exist in the specific model.
The first decision is not: Which vault impresses me? It is: What right do I have to which metal—and against whom can I enforce it?
The first decision is not the vault. It is the enforceable right to specifically identified metal.
What Defines a Strong Precious-Metals Solution
01Legal ownership
02Durable evidence
03Independent access
04Tested exit
A strong structure gives each location a defined role.
Liechtenstein execution and Swiss bonded storage form our European core solution. Dubai and Turkey open the GCC axis; Singapore and Hong Kong extend the options in Asia.
Switzerland
Professional execution through our selected partner in Liechtenstein with physical storage in a Swiss bonded warehouse.
Dubai
Dubai investment route from EUR 100,000 with professional storage in a bonded warehouse in Turkey.
Singapore
Singapore and Hong Kong add a strong Asian axis to an international custody strategy, available on request.
Switzerland: Our Core European Solution
For many entrepreneurs and wealthy families, Switzerland is an excellent jurisdiction for storing physical gold. Its strength lies not only in its international reputation, but in an ecosystem built over decades across refining, assaying, trading, secure logistics, private vaulting, and clearly regulated customs procedures.
Swiss Precious Metal Control oversees technical requirements for precious-metal goods, melt products, and certain commercial activities. The Federal Office for Customs and Border Security describes a regulated control, licensing, and testing system. This provides a strong quality framework for the Swiss precious-metals ecosystem, but it does not determine the quality of any individual private custody agreement. (FOCBS: Precious Metal Control, FOCBS: Goods Traffic)
Tax treatment also requires precision. Under Article 23(2)(12) of the Swiss VAT Act, certain transactions involving qualifying investment gold are exempt from VAT. Subject to the statutory conditions, this includes investment gold with a minimum fineness of 995 thousandths, in prescribed bar or plate form and bearing the required markings. The exemption does not automatically cover every product containing gold or every related service. (Amendment to the Swiss VAT Act, AS 2024 438; effective January 1, 2025)
Why Swiss Bonded Storage Stands Out
Swiss freeports are officially defined facilities where uncleared and untaxed goods may be held temporarily under customs supervision. If the goods are later imported or re-exported, the corresponding customs procedures apply. Open customs warehouses are a different procedural category and should not be treated as interchangeable with freeports. (FOCBS: Freeports, FOCBS: Open Customs Warehouses)
For qualifying investment gold, a freeport is not automatically the central tax advantage because transactions in legally defined investment gold may already be exempt from VAT. A customs-warehouse procedure may be more relevant for silver, platinum, palladium, transit inventories, or holdings intended for re-export. Marketing “tax-free gold in a Swiss freeport” as a blanket proposition therefore compresses a decision that must separately consider product form, owner, movement of goods, and eventual withdrawal.
Investing Through Liechtenstein, Storing the Physical Metal in Switzerland
For Europe-oriented private clients, entrepreneurs, and families, a two-step structure may be particularly compelling: the investment or settlement takes place through Liechtenstein, while the physical metal is stored in Switzerland.
Under their customs treaty, Liechtenstein and Switzerland form a common customs and economic area with an open border. Liechtenstein VAT law also contains an exemption modeled on the Swiss rule for legally qualifying investment gold with a minimum fineness of 995 thousandths and the required markings. This makes a two-step structure possible in principle—provided that an identified Liechtenstein counterparty, duly authorized for its activity, actually offers the arrangement and the Swiss custodian contractually recognizes the client's ownership and delivery rights. The customs union and parallel VAT rules facilitate cross-border movement of goods, but they do not prove the commercial availability of a particular structure, nor its ownership, insolvency, or personal tax benefits. (Swiss FDFA: Switzerland–Liechtenstein Relations, Liechtenstein VAT Act, Article 23)
The strategic benefit is not a blanket promise of tax savings or anonymity. It can arise from a functional separation:
- Liechtenstein may serve as the investment, contractual, or settlement layer.
- Switzerland performs the physical custody function.
- Evidence of ownership, bar allocation, insurance, audit, and exit can be documented as separate review tracks.
The additional Liechtenstein step must have a specific purpose. It may be appropriate when a suitable Liechtenstein contracting or settlement partner provides demonstrable access, a necessary administrative link, or an appropriate ownership structure. Without that purpose, direct Swiss acquisition and custody may be stronger: fewer counterparties, fewer interfaces, and a shorter documentary chain. Any arrangement should be rejected if the Swiss custodian does not adequately recognize the owner, the bars are not specifically allocated, or the exit depends entirely on the original intermediary.
Consider a DACH-region entrepreneur who deliberately does not want to hold physical gold with his main bank. Switzerland is geographically accessible and institutionally familiar. At the same time, he wants the acquisition and settlement process professionally organized outside the existing banking relationship. A Liechtenstein–Switzerland structure can reconcile these objectives. It becomes resilient, however, only when the entrepreneur knows not merely where the gold is stored, but also which company sold it, when title transferred, who recognizes him as owner, and how delivery or sale is initiated.
Switzerland is therefore not the conservative fallback in an international comparison. For many European wealth architectures, it is the natural starting point.
Under time pressure, European proximity may also make it easier to coordinate contracts, original documents, powers of attorney, and potential physical delivery. The actual timeline will depend on the provider, bank, identity review, transport, and documentary record and should be tested in writing before purchase. Anyone who lives and operates primarily in Europe should therefore assess Switzerland first—and add a Liechtenstein layer only when it performs a demonstrable function.
For many European wealth architectures, Switzerland is the natural starting point.
Dubai and Turkey: Our GCC Solution from EUR 100,000
For clients whose life, companies, or banking relationships are centered in the UAE, we offer a Dubai investment route from EUR 100,000 with storage in a bonded warehouse in Turkey. It combines access to Dubai’s dynamic gold market with a distinct international custody axis.
For entrepreneurs whose home base, companies, banks, and advisors are already in the UAE or wider GCC, this operational proximity can be decisive. Vault visits, document resolution, secure logistics, sales, and banking coordination may all be handled within the same regional axis. That is a real advantage—and a far more defensible proposition than the broad slogan “tax-free gold in Dubai.”
The UAE has defined boundaries. Under Article 36 of the VAT Executive Regulation, the supply of investment precious metals is zero-rated where gold, silver, or platinum is at least 99 percent pure and tradable in global bullion markets. The VAT treatment of an import must also be reviewed under the applicable import rules. Jewelry, collectibles, fabrication, and non-qualifying products may receive different treatment. Legally, zero-rating is also distinct from a general exemption. (UAE Federal Tax Authority: VAT Executive Regulation)
A reverse-charge mechanism also applies to certain domestic B2B transactions between VAT-registered businesses. This must be distinguished from zero-rating for qualifying investment metals and should not be described as a blanket retail exemption. (UAE Ministry of Finance: Reverse Charge for Precious Metals and Stones)
DMCC Tradeflow can register possession and title information for goods held in approved warehouses and can issue electronic warehouse receipts. Title to registered goods may be transferred through Tradeflow or pledged in favor of a financier. That creates an additional due-diligence question for the owner: Which rights and encumbrances are actually registered? Registration alone proves neither physical segregation nor insolvency protection. (DMCC Tradeflow)
Dubai is particularly strong when it performs an operational role: GCC access, market liquidity, regional proximity, and coordination. For an entrepreneur with a UAE company, local banks, and recurring capital needs, a regional custody and sale channel may simplify execution. Timelines, bank review, and settlement must still be established in writing in advance. An owner who does not genuinely use the GCC axis should instead ask whether the additional jurisdiction creates more friction than operating capacity. In either case, the specific custody agreement determines the strength of the long-term storage arrangement.
Dubai is strongest when the location serves a real operational GCC function.
Singapore and Hong Kong: Asian Options on Request
For internationally positioned families and family offices, Singapore and Hong Kong add a strong Asian custody axis. Singapore combines clear rules, specialist security logistics, and a growing institutional gold market; both locations are available on request.
The tax rule is precise: the import and local supply of qualifying Investment Precious Metals are exempt from Singapore Goods and Services Tax. For gold bars, ingots, and wafers, the tax authority generally requires at least 99.5 percent purity, international tradability as bullion, an accredited quality mark, and a non-decorative, non-collectible character. Jewelry, scrap, numismatic products, and products from non-qualifying refiners may remain taxable. Storage, transportation, testing, and advisory services do not automatically become GST-exempt merely because the metal qualifies. (IRAS: Supplies Exempt from GST/charging-gst-(output-tax)/when-is-gst-not-charged/supplies-exempt-from-gst), IRAS IPM Guide)
The exemption does not make the metal invisible to customs. Depending on mode of transport, value, weight, and whether the metal is commercially shipped or personally hand-carried, Singapore Customs still requires declarations, permits, and supporting records. Hand-carried imports must proceed through the Red Channel, with any required import permit, invoices, and—where available—certificates and other supporting evidence. (Singapore Customs: Importing Investment Precious Metals)
Singapore's Ministry of Law supervises registered precious-metals dealers for anti-money-laundering and counter-terrorist-financing purposes. Registration does not confirm a dealer's solvency, custody quality, or the client's ownership position. (Singapore Ministry of Law: Regulatory Regime, Regulation Coverage)
Consider an internationally mobile entrepreneurial family with gold stored in Switzerland and a planned acquisition in Asia. The first purchase-price installment is due in twelve days. The Swiss custodian can sell, but the proceeds would first be credited to a European reference account. The receiving bank in Singapore has not yet pre-cleared the ownership and source-of-funds documents. The family must now choose: initiate the existing Swiss sale route and finance a timing reserve, postpone the transaction, or first build a reliable Asian settlement axis. In this situation, Singapore creates genuine optionality only if the custodian, bank, and authorized representatives have tested the complete process before the next closing. Otherwise, geographic diversification becomes another operational interface.
Singapore is continuing to develop its institutional gold infrastructure. In June 2026, an OTC clearing system for “Loco Singapore” was announced, with launch planned by the end of 2026. Separately announced custody services from the Monetary Authority of Singapore are intended for foreign central banks. Clearing is market infrastructure; neither announcement establishes a custody offering already available to private clients. (Reuters: Singapore gold clearing initiative)
Singapore's value lies in establishing a deliberate Asian axis. Families with companies, banks, relatives, or future wealth decisions in Asia can create geographic access and settlement capacity there. This becomes particularly relevant when authorized family members, advisors, and banks need to act in an Asian time zone and legal environment. For an owner anchored exclusively in Europe or the GCC, distance and additional document maintenance may outweigh the diversification benefit.
Singapore creates optionality only when the family genuinely needs an Asian execution axis.
Four Locations—Four Strategic Opportunities
The comparison explains why naming an overall winner would be unhelpful. Switzerland may be the best core solution for a European entrepreneur. Dubai may become operationally more important for that same entrepreneur after a permanent move to the UAE. Singapore may create a genuine second access point for a family with business and succession interests in Southeast Asia.
The right jurisdiction follows the function—not the flag.
The right jurisdiction follows the function, not the flag.
Three different functions, not three competing countries
Show or close comparison table
Multiple Locations Create International Optionality
As international wealth grows, a second custody axis can become valuable. Switzerland often forms the European core, while Dubai–Turkey or Singapore–Hong Kong can extend it along the owner’s business, family, and geographic footprint.
Consider a family with assets in Europe and Asia evaluating a split between Switzerland and Singapore. On paper, the diversification looks compelling. The detailed review, however, reveals that both positions are held through the same intermediary, released through the same platform, and controlled under the same central power of attorney in the event of death. The metal sits in two countries, yet the family's ability to act still depends on a single access point.
A multi-location structure is most defensible when it reduces a specific bottleneck:
- geographic access across two places where the family genuinely lives or does business;
- dependence on a single contracting party or custody group;
- concentration of liquidation routes through one dealer or bank;
- succession and power-of-attorney risks;
- operational dependence on one currency, time zone, or logistics chain.
It is less compelling when it merely creates the appearance of international diversification. Additional locations bring costs, reporting, repeated identity and source-of-funds reviews, document maintenance, and coordination. For smaller allocations, one exceptionally well-documented Swiss solution may be stronger than an artificially fragmented three-country structure.
Diversification does not begin with the number of vaults. It begins with the independence of ownership, access, and exit paths.
For an internationally mobile family, that can force an uncomfortable decision. One parent lives mainly in Europe, adult children manage investments from Singapore, and family liquidity is organized across two banks. If the owner becomes incapacitated, a second vault will not solve the problem. The family needs effective powers of attorney, current identity and source-of-funds documentation, recognized representation rules, and at least one independently executable sale route. Before dividing the holding, the family must decide: Are these access routes genuinely independent and usable by the next generation—or should it first approve one cleanly documented Swiss core solution and defer the Asian complement?
Diversification begins with independent ownership, access, and exit paths—not with the number of vaults.
What Professional Custody Looks Like
Insurance protects the physical holding, independent audits create transparency, and a defined sales process makes gold liquid when required.
Insurance may cover loss, damage, or theft under defined conditions. It does not automatically protect against provider insolvency, government action, contractual disputes, mysterious disappearance, or every transportation risk. What matters is who holds the policy, who is the beneficiary, what limits and deductibles apply, and whether coverage is calculated per client, per event, or in aggregate across all holdings.
An audit may count the physical inventory or merely inspect records. It may be comprehensive or sample-based. It may reconcile metal inventories against client liabilities—or only confirm that metal was present in a vault on a specific date. The World Gold Council recommends, among other measures, professional independent custody, regular independent audits, inventory reconciliation, and appropriate insurance coverage for retail gold products. The actual audit report must still disclose what was tested.
Liquidity exists only when the process can be executed. Can the owner sell to multiple dealers, or only to the original provider? Must a large bar be melted down or exchanged before a partial sale? Does a new identity and source-of-funds review begin upon transfer? If the metal leaves a recognized chain of custody, does it lose immediate marketability and require renewed authenticity and fineness testing?
This is where an entrepreneur feels the difference. The gold may have significant market value and still fail to fund a transaction in time. The cost of error is not the storage fee. It is lost time, weaker negotiating leverage, or a missed closing.
For time-sensitive liquidity, the release rule should be unambiguous: Do not count gold as an available reserve until the sale route, receiving bank, required documentation, fees, settlement account, and target timeline have been confirmed in writing or tested in practice. Until then, the position remains a store of wealth—but not committed transaction liquidity.
Insurance, audit, and liquidity are three separate promises, each requiring its own evidence.
Our Quality Review Before Implementation
Before implementation, we clarify the decisive ownership, custody, insurance, and exit points with the partners involved.
This quality review is part of our preparation: we connect the right international route with clear ownership, professional custody, and a defined path to sale.
Professional preparation creates clarity—from acquisition through custody and a future sale.
A suitable solution exists for every international wealth axis.
The right structure connects personal objectives with professional acquisition and international custody.
DACH entrepreneur
Liechtenstein combines professional execution with physical storage in a Swiss bonded warehouse.
LIECHTENSTEIN × SWITZERLANDEntrepreneur with a GCC axis
From EUR 100,000, the Dubai investment route opens the GCC axis with bonded storage in Turkey.
DUBAI × TURKEYFamily with an Asian axis
Singapore and Hong Kong extend international custody for families and founders with an Asian focus.
ASIA ON REQUESTOur international precious-metals solutions
Together with a selected partner, No Borders Founder specializes in facilitating access to physical precious metals and international custody solutions. Unlike a conventional domestic bullion purchase, we connect acquisition, individual bar allocation, and bonded storage from the outset.
Liechtenstein & Switzerland
Professional execution in Liechtenstein with physical storage in a Swiss bonded warehouse.
Dubai & Turkey from EUR 100,000
A GCC-focused investment route combined with international bonded storage in Turkey.
Singapore & Hong Kong
Selected Asian custody solutions are available on request.
We personally identify which solution best fits your wealth structure.
Swiss bonded storage
Our European core solution for professional custody outside the conventional banking relationship.
Liechtenstein → Switzerland
Execution through Liechtenstein with physical storage in a Swiss bonded warehouse.
Dubai → Turkey
A GCC investment route from EUR 100,000 with storage in a bonded warehouse in Turkey.
Singapore & Hong Kong
Asian custody solutions available on request.
Our quality review before implementation
- Who is selling the gold, and when does legal title transfer?
- Do I own specific bars, or only a claim to a quantity of metal?
- Which serial numbers, weights, fineness levels, and refiners are assigned to me?
- What does “segregated” mean physically and in the accounting records under this agreement?
- May any party lend, pledge, substitute, or otherwise use the metal?
- What liens, rights of retention, or rights of setoff exist?
- Who is the actual vault operator, and which sub-custodians are involved?
- What does the independent auditor test, as of which date, and how often?
- Which losses does the insurance cover, which does it exclude, and who receives the proceeds?
- How do physical delivery, relocation, and cross-border transport work?
- Through whom may I sell, what fees and spreads apply, and when are proceeds paid?
- Who may act upon death or incapacity, and which documents will be required?
Answers should be written, contract-specific, and tied to the actual owner, custodian, and location.
Gold storage in Switzerland, Dubai, and Singapore
Which precious-metals solutions does No Borders Founder offer?
We facilitate access to physical precious metals through a selected partner. Tested routes include Liechtenstein execution with Swiss bonded storage, a Dubai investment route from EUR 100,000 with bonded storage in Turkey, and Singapore or Hong Kong on request.
How Does the Liechtenstein–Switzerland Route Work?
Investment and execution are handled through our selected partner in Liechtenstein, while the physical precious metals are professionally held in a Swiss bonded warehouse.
How Does the Dubai–Turkey Solution Work?
From an investment of EUR 100,000, we combine market access through Dubai with professional storage in a bonded warehouse in Turkey—particularly relevant for founders and families with a GCC focus.
Which Asian Options Are Available?
Singapore and Hong Kong are available on request as Asian custody options for internationally positioned founders, families, and family offices.
What Makes This Different from a Conventional Domestic Gold Purchase?
We connect the acquisition of physical precious metals with clear ownership allocation and international bonded storage from the outset, positioning gold as a professionally structured component of an international wealth-protection strategy.
Sources & evidenceOpen 20 sources and notes
Source cutoff September 14, 2026. Tax, customs, AML/CFT, custody rules, and provider terms can change and must be checked again before a transaction.
- London Bullion Market Association · Precious Metal Accounts↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss FOCBS · Precious Metal Control↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss FOCBS · Precious Metals Control in Goods Traffic↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss Confederation · VAT Act amendment, AS 2024 438↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss FOCBS · Customs free warehouses↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss FOCBS · Open customs warehouses↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Swiss FDFA · Switzerland–Liechtenstein relations↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Liechtenstein Legal Gazette · VAT Act, Article 23↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- UAE Federal Tax Authority · VAT Executive Regulation↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- UAE Ministry of Finance · Reverse charge for precious metals and stones↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Dubai Multi Commodities Centre · Gold ecosystem↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- DMCC · Gold and Precious Metals Fact Sheet↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- DMCC · Tradeflow↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- IRAS · Supplies exempt from GST↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- IRAS · GST Guide on Exemption of Investment Precious Metals↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Singapore Customs · Importing Investment Precious Metals↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Singapore Ministry of Law · Regulatory regime for regulated dealers↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Singapore Ministry of Law · Regulation coverage↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- Reuters · Singapore to establish OTC gold clearing system↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
- World Gold Council · Retail Gold Investment Principles — Specific Guidance↗ (opens in a new tab)Primary or specialist source used in the article; its relevance and limits are stated in the corresponding section.
Save, continue, or export.
This analysis was updated on .
MY ANALYSESNo saved analysis yet
Your reading list stays in this browser. No account and no data transfer to us.
Use “Save for later” to build your personal analysis collection here.
Remember interests on this device. Push notifications will be offered after WonderPush is activated.
Understand the terms used in this analysis
- Decision architecture
- The coordinated connection of legal, tax, operational, banking, and personal decisions.
- Jurisdiction
- The legal and regulatory system under which a structure, person, or transaction is assessed.
- Substance
- A structure’s genuine economic and operational presence, beyond formal registration.
- Access risk
- The risk that formal ownership remains while capital, accounts, documents, or decision rights become practically unavailable.
How would you like to continue this analysis?
Further perspective from Alexander Erber
New analysis and international developments, assessed from an entrepreneurial and international perspective.
TOPIC UPDATESPush notifications will follow with WonderPush.Coming soon
